ServicesTerm Life Insurance
Term Life Insurance in Tyler, Built Around the Right Term Length
With term life, the insurer owes your named beneficiaries the face amount if your death falls inside the policy's span of years. We help you choose the amount and term length that fit your debts and your children's ages. Then we check every beneficiary line and rider before you sign.
What term life does, and when it fits
Term coverage runs for a set span of years, anywhere from a decade up to three, and the premium is locked at the same amount from the first payment to the last. If you die inside that span, the insurer pays the face amount to the beneficiaries you named, generally free of income tax. If you outlive it, the coverage ends and nothing comes back to you unless you added a return-of-premium rider.
Term fits best when the obligation you are covering will run out on its own schedule. Think of a loan with a final payment date, children who will grow up and leave school, a business note, or the paychecks a spouse would need for a known number of years. Per dollar of coverage, it costs far less than whole life or universal life, which is why most people start here.
Term goes wrong in the small details. A 20-year term bought against a 25-year mortgage leaves a five-year gap. A beneficiary form that still names an ex-spouse, or names a minor child directly, can stall a claim for months. Those lines are where we spend our time.
What we handle on a term life policy
- Sizing the face amount
- We add up what would need to be covered: the mortgage balance, other debts, years of income, childcare and college. That total becomes the face amount, not a round number picked because it sounds right.
- Matching the term to the need
- We line the term up with the latest date a need ends. If your youngest is 4 and the mortgage has 22 years left, a 20-year term falls short, and we show you that gap before you apply. Sometimes two smaller policies with different terms cost less than one large one.
- Beneficiary and ownership setup
- We name primary and contingent beneficiaries with full legal names and percentages that total 100. Minor children cannot receive the money directly, so we talk through naming a trust or a custodian instead. We also confirm who owns the policy, since ownership affects control and taxes.
- Riders, read one at a time
- Waiver of premium, accelerated death benefit, child term and return of premium each change what the policy does and what it costs. We explain each one and leave off the ones that do not fit you.
- Conversion rights and deadlines
- Most term contracts carry a conversion privilege: you can switch to whole life or universal life with no fresh health questions, as long as you act before a cutoff printed in the policy. We flag that cutoff for you, because letting it pass is a common way people lose the chance to keep coverage if their health changes.
Signs it is time to look at term life
A new mortgage or business loan
If someone else would be left holding the payment, coverage sized to that balance keeps the debt from landing on them.
A new baby
Each child adds years of costs that your income covers today.
Coverage only through your job
Group plans through an employer commonly pay one or two times your annual salary, and the coverage usually ends when you leave. It is a starting point, not a plan.
An old term policy about to expire
When the level period ends, premiums usually climb every year. If your term runs out soon and you still need coverage, it is worth comparing options while your current health still counts in your favor.
Beneficiaries that no longer fit
A divorce, remarriage or death in the family can leave the wrong person named. The insurer pays whoever is on the beneficiary form, not whoever your will names.
What moves the premium on term life
The insurer prices term life from mortality tables and your underwriting results, so no honest agent can name your premium before those details are known. What we can do is show you which choices push the price up or down, and where a small change saves money without opening a gap in coverage.
Age and health
The premium is set at your age on the application date and locked for the term. Blood pressure, cholesterol, weight and conditions such as diabetes decide your rate class.
Tobacco and nicotine
Cigarettes, vaping and chewing tobacco put you in a tobacco class, which costs much more. Carriers test for nicotine, so it is better to disclose it up front.
Term length and face amount
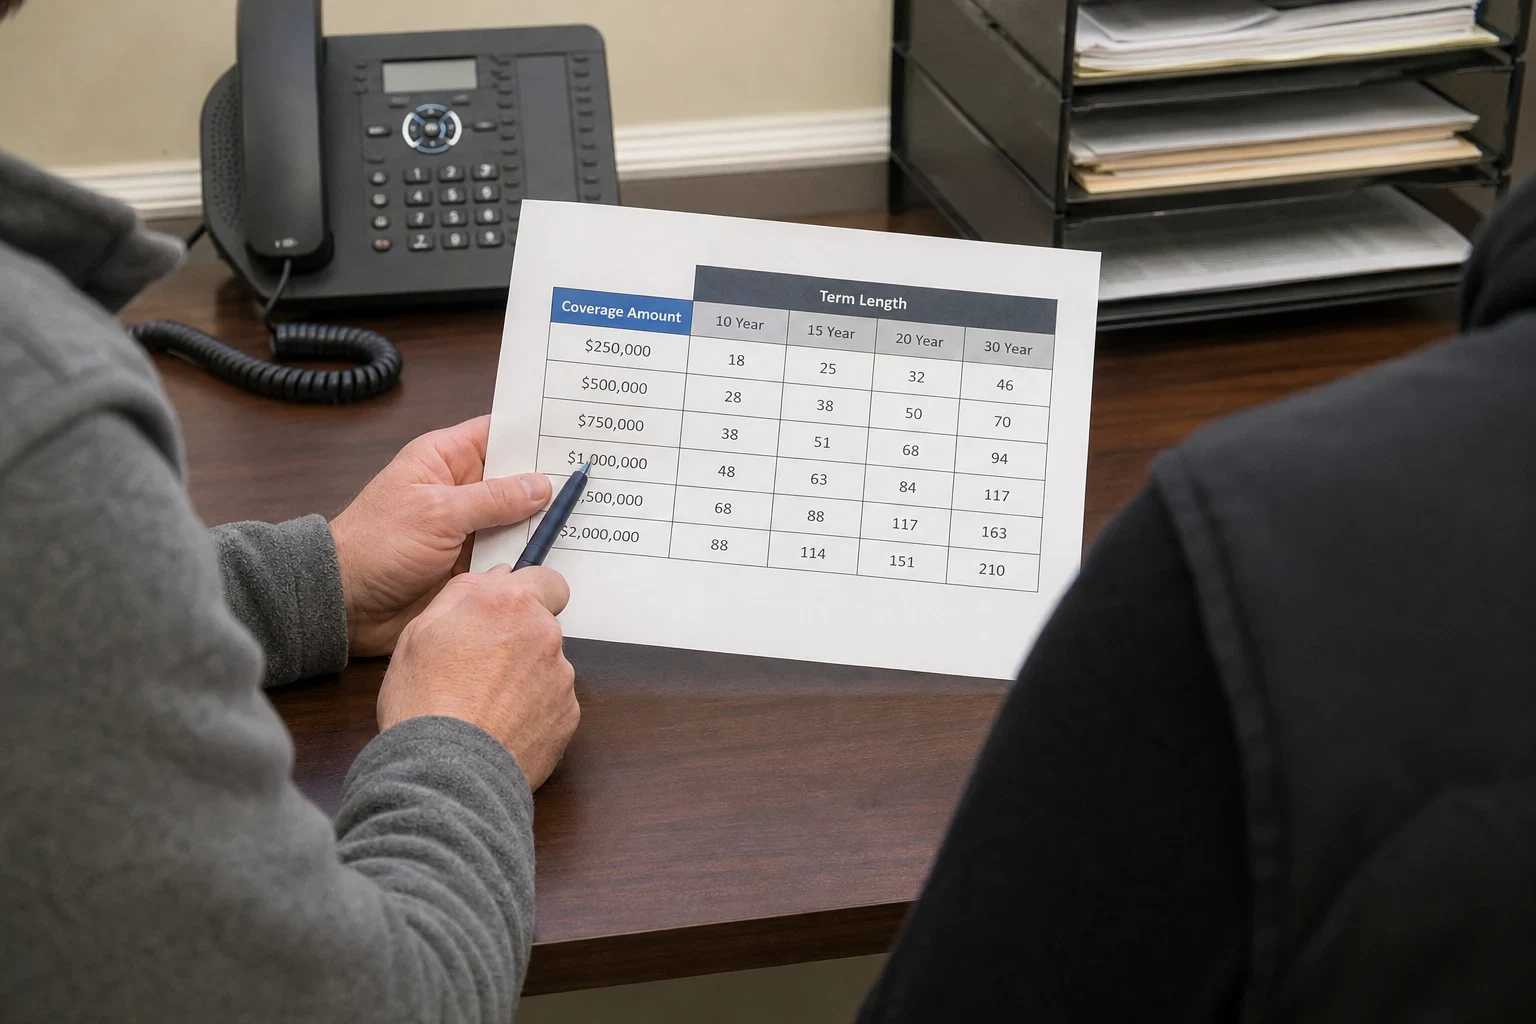
A 30-year term costs more each year than a 20-year term for the same amount, because the insurer carries the risk into older ages. Amounts are often priced in bands, so a slightly larger policy can cost very little more.
Riders
Each rider adds to the premium, and return of premium can raise it substantially. We show you the price with and without each one so you can decide.
Work and pastimes
A hazardous line of work, or a pastime like piloting small aircraft or deep diving, can move you to a higher rate or bring a written exclusion into the contract.
How a term life application runs
- 1
A phone conversation about the need
We start with your debts, income, dependents and any coverage you already carry. From that we work out a face amount and term length, and we explain how we got each number.
- 2
A realistic rate class
Your age, health and tobacco use place you in a rate class, from preferred down to standard. We quote at a class you are likely to qualify for, so the premium does not jump after underwriting.
- 3
Application and underwriting
The application asks about medical history, medications and lifestyle. Depending on your age and the amount, the carrier may order a short paramedical exam with blood and urine samples, often done at your business or wherever suits you, and will review prescription and medical records. Complete answers matter, because a misstatement can let the insurer contest a claim during the first two years.
- 4
Delivery and a final check
Once the carrier issues the contract, we read each section of it together: face amount, term, premium, riders, beneficiaries and the conversion cutoff. If anything differs from what you applied for, we raise it before you accept.
Term life questions we hear in Tyler
What happens when my term ends?
Coverage stops unless you renew or convert. Many policies allow yearly renewal without a new exam, but the premium rises each year and gets expensive quickly. Converting to whole life or universal life before the conversion deadline keeps coverage in place without new medical questions.
Is term life wasted money if I outlive it?
No more than car coverage is wasted in a year without an accident. You paid for protection during the years your family relied most on your income. If you would like some of those premiums back at the end, we can quote a return-of-premium rider and show exactly what it adds to the cost.
How much coverage do I actually need?
Start with what you owe. Add the number of years your spouse or children would depend on your paycheck, plus large bills still ahead, such as tuition. Then subtract savings and any coverage you already hold. We work through those numbers with you by phone instead of using a flat multiple of salary.
Can I just rely on the life insurance from work?
You can keep it, but it usually ends or shrinks when you change jobs, and the amount may not match your debts. A personal term policy stays with you wherever you work. Many of our clients carry both.
Do you work with clients outside Tyler?
Yes. We help clients in Whitehouse, Lindale, Bullard, Chandler and the surrounding area. Most of the conversation happens by phone, so distance is rarely an issue.
Get the term and the paperwork right
Tell us what you need covered and for how long. We will work out the face amount and term with you and explain each line before you apply.